Reincarnation

In the coming weeks we will likely hear James Carville’s name more often. Carville earned his fame as political adviser to the Democrats (his wife Mary Matalin was an equally famous Republican adviser), and is known for his pithy advice, having told the Clinton Democrats that ‘It’s the economy, stupid!’, and recently counselled them to ‘play dead’, whilst the Trump Republicans continue to make mistakes.   

It might be expected that Carville will become sought after for his views on the forthcoming mid-terms, but it is more likely we will hear him quoted in relation to the bond market. In the context of mostly dull economists, journalists in need of a good bond market quote turn to Carville who stated that ‘’I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.”  

He said it in 1994, when US bond yields had pushed out to 8%, forcing Treasury Secretary Robert Rubin into a four-year deficit reduction programme – built on a rare moment of constructive bipartisanship – that halved bond yields and eventually produced a budget surplus. That kind of policy foresight, bipartisanship and political leadership is rare today; what endures is the bond market’s reputation as a powerful, intimidating beast.   

Today, the bond market is back, and it is intimidating investors, governments and soon, the public. For all too long, bond buying by central banks had a soporific effect on bond prices, dulling them to the rising fiscal risks that have now enveloped most of the major economies. A couple of years ago we compared the effect of central bank liquidity to the storyline in the Danish film ‘Druk’ (which I recommend) where a group of teachers experiment with a permanent state of tipsiness. Central banks are now withdrawing liquidity, bond markets are sober and alive to the world and are pointing out various truths.   

The first of these is that the ‘debt purgatory’ has commenced, precisely when the US Treasury Secretary made a series of failed interventions in currency and bond markets, demonstrating – in the spirit of Carville’s quote – that the bond market is more powerful than the government. In that respect, a threshold has been crossed where finance ministers may no longer be able to run near record deficits (in the context of economic expansion) and gargantuan debt levels. Scott Bessent, who has displayed a fetish for controlling market prices, may soon need either to start trimming spending, or to raise taxes (unlikely).   

In France, the debate on the budget starts in earnest next week, in the context of the highest spread between French and German bond yields since 2012, and the woeful performance of the CAC 40 (in the past three years the Spanish and Italian stock markets have outperformed it by close to 90% and 75% respectively). To that end, debt, deficits and bond markets will dominate politics. For example, a recent Institute of International Finance (IIF) shows that the US spends more on interest payments (4% of GDP) than at any point in the last thirty years. In that context, it is likely that bond markets may only be calmed when governments make a serious effort to mend their finances, and when central banks enact further rate increases. This will prove to be a tough run into and beyond Christmas.   

The second germane element of the rise in bond yields (which are only returning to their 150 year averages), is reflexivity, a word coined by George Soros to describe the ways in which moves in asset prices can cause effects in the real economy (and in other asset prices).   

Higher bond yields should curb risk appetite and slow the economy. In previous economic cycles the thinking was that higher bond yields led to higher mortgage rates and thus a sluggish property market. The difference today is that many of the ‘Baby-Boomer’ generation have paid off their mortgages, or locked in mortgage rates at low levels, and the US middle-class has never been wealthier, and less rate sensitive (for example a new book ‘The Everywhere Millionaire’ by Owen Zidar and Eric Zwick traces the origins of the wealth of the 3 million Americans with over USD 25 million in wealth each and this effect is evident through the rest of the US wealth pyramid).   

In other areas, the reflexive effect of bond yields may just be beginning and is already manifesting itself in the very riskier reaches of the corporate bond market (high yield/CCC rated bond yields are rising) and may soon take its toll on cyclical commodity prices (copper and oil).   

The puzzle, optically at least, is that US equities have not registered the rise on bond yields. However, within the equity market, the many stocks have been weak over the past month (for example household ‘names’ Goldman Sachs and Boeing have fallen close to 20% since mid July) but headline indices have been kept higher by the small number of mega-cap AI related stocks (Intel, NVIDIA). Unlike US households who have in general been deleveraging, the AI complex is busy piling on debt. A sign of this is that UBS recently initiated a new publication, the ‘AI Debt Financing Monitor’. Experience tells me that the initiation of publications that herald the arrival of new asset classes is always a warning sign. To that end, the time to buy bonds is when yields rise to levels that brings hyperscaler debt raises to a halt.   

Have a great week ahead, Mike   
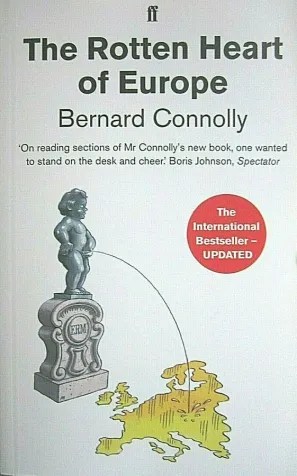
The Rotten Heart of Europe

One of the first books I read that helped to explain how Brussels worked was Bernard Connolly’s ‘The Rotten Heart of Europe’, published in 1995. It was a massive hit (in the UK) and hugely controversial. Indeed, a second edition came with a cover recommendation from the then editor of the Spectator Boris Johnson (‘one wanted to stand on the desk and cheer’).  

The book did much to propagate Euroscepticism in British politics, and we might trace some of the roots of Brexit to it. With some irony, Brexit showed that the Commission can function in a forceful way when a crisis befalls it. However, as is well documented the challenge for the EC is to now step up a level and reinforce itself for a multipolar world where it will compete more acutely with China and the US, with at the same time Russia snapping at its heels.  

Connolly’s book came to mind a week ago when speaking at an investment conference. I was joined on a panel by economists and policy makers from Italy, Spain and Portugal, so that together we made up a representative group of the euro-zone periphery countries hit hardest (though Greece suffered the most) by the euro-zone debt crisis.  

Each of the periphery economies has had a remarkable turnaround – Italy is a bastion of political stability, Spain is the fastest growing of the large economies and Greece, Portugal and Ireland are arguably ‘too hot’ in terms of the rate of growth and price inflation they experience. What is telling is the signal from bond markets – yields for Italy, Spain and Greece for example, are below those of France and the UK, and Ireland is nearly on a par with Germany.  

In that respect, the tables have been turned. It is not forgotten how Angela Merkel and Nicola Sarkozy upbraided the lazy Mediterraneans in the 2010’s. Now, the three large countries at the heart of European history – the UK, France and Germany, are struggling, and to unkindly borrow Bernard Connolly’s title, constitute the ‘rotten heart of Europe’ 

They share common problems – sluggish, low growth, an inability to foster sustained private investment, political instability in the face of electorates who are in thrall to the easy solutions of populist parties. The reaction to last week’s triumph of the AfD (Alternative fur Deutschland) in Saxony-Anhalt is an example, and it may mean that Frederich Merz suffers the fate of Keir Starmer should his coalition collapse or his party cast him aside in favour of a younger leader.  

Though the tempo of growth is picking up in Germany, the UK and France, it will not rescue the leaders of the large economies. An additional complexity is that trading partners and allies are turning against them – China is exporting its manufacturing over-capacity to the German consumer and the special relationship that characterized US-UK diplomacy has all but withered away. The prospect that the White House might favour Argentina’s case for sovereignty over the Falkland Islands is a stunning case in point.  

Unlike France, the British and German economies suffer from a similar failure to upgrade their ‘production capital’ – investment in research, skills, new technologies and to an extent, manufacturing capacity. Both are behind France in terms of military power, but France is a leader in over-regulation. The fate of these three great nations has already inspired an endless flow of analyses, ideas and suggestions – the best of which from Mario Draghi, seems to be ignored.  

The sole thought I have to add, is that incumbent, centrist politicians in all three countries appear to ignore the increasingly obvious lesson that the rules of the geopolitical game have changed, and as we have referenced before in this note, we live in an ‘age of predators’, and consequently prey (Starmer). In this regard, new ideas are not the solution, but a change of method is. That method is more singular, less consensus led and aggressive. Edouard Philippe in France and Andy Burnham are its test cases, we will know by next May if they learn this lesson, and if not, Europe is in dire straits.  

Have a great week ahead, Mike  
Debt Purgatory

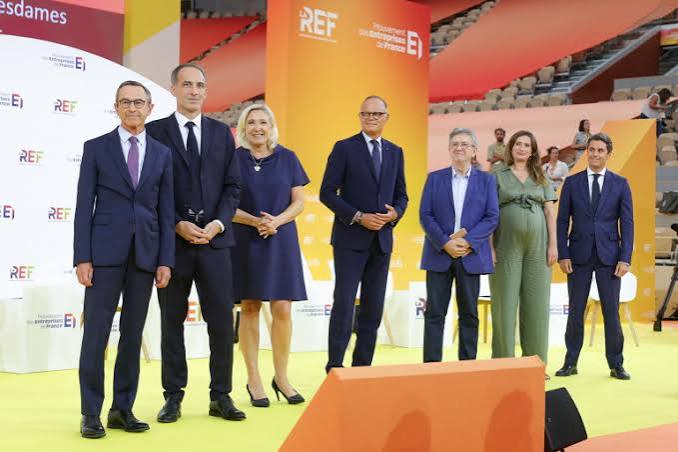
Roland Garros is one of the more stylish and elegant parts of Paris, and not a bad location to discuss finance and economics. Unfortunately, France’s political elite did not rise to the occasion. At the end of last week, (MEDEF), the large French business network gathered the principal candidates for the 2027 presidential campaign to listen to their views on the economy, and in particular their policies to pare back France’s gargantuan fiscal deficit and debt load. With a few exceptions, they disappointed.  

The candidates for the far-left (Jean-Luc Melenchon of La France Insoumise) and far-right, Marine Le Pen of the Rassemblement Nationale, appeared to treat the event as a light-hearted post-holiday chat show, and not a forum to debate the faultline that could pitch the euro-zone into another debt crisis.  

Though France’s presidential election is far off (the first round is on 18 April 2027), international investors need to pay close attention to it, both as a specific risk factor for bonds, foreign exchange and equities, and as a harbinger of what might befall most of the other major economies.  

In this respect, France has at least two things in common with the US. First, its weak finances. The budget deficit has been stuck at 5%, a level historically associated with a recession, and debt to GDP is on course to hit 120% according to the OECD. Second, there is no appetite to tackle this dire fiscal situation. In the US, there is little prospect of corrective tax hikes or spending cuts, and the Trump administration appears to have a fetish for intervening in markets.   

In France, three governments have been consumed by the process of setting a budget, and there is no political nor popular will to set France’s finances on a sustainable track. What is worse is that wild, populist suggestions that France could cancel the debt that the Banque de France holds (as a result of quantitative easing) are being aired in the media. France’s political class and populace are not known for their financial literacy, and the belief in some quarters that debt can be magicked away is dangerous and sets the economy up for a sharp reality check.  

Having witnessed the brutal effect of a debt crisis and the subsequent austerity on the Irish economy from 2010 onwards, French policymakers and its public are badly unprepared for what may come. Government spending at 57% of GDP is comparatively huge, and much of this goes on social welfare (healthcare and pensions).  

Unlike the US, France is not enjoying an AI capital expenditure fuelled wealth effect, and the notion that it might act to structurally boost economic growth is anathema to nearly all of its politicians. In a demonstration of moral hazard, France has accumulated debt at a pace and amount more than any other euro-zone country, without much protest from the ECB. 

Markets however, are reacting. French ten-year bond yields have just passed Italy’s. While long-bond yields in Japan, the US and UK have all broken higher to multi-decade highs, the re-rating of France is troubling. For international investors, France’s changing status, from a core, safe haven, to a periphery market is one of several signals of a coming debt purgatory – a long period where indebtedness dominates markets, government politics and geopolitics.  

For European policy makers, the fact that France is the indispensable nation on geopolitics, defence and military innovation complicates matters because it means that politically, in the context of German underperformance, France is harder to corral into a fiscal straightjacket in the same way the European Commission did with Greece, Ireland and Spain. On the European political stage, there is no-one fiscally credible politician who might stand up to France and avert the potential for contagion across the euro-zone.  

If for instance, both Melenchon and Le Pen make it through to the second round of the presidential election, bond investors will desert France, French bank share will collapse, luxury goods firms will become bargains, and the euro will likely fall. Bond investors will likely rush to the few safe havens the euro-zone offers – Germany, the Netherlands and Ireland as well as assets in ‘old’ periphery countries like Norway and Switzerland.  

More broadly, a continued rise in French yields, in the face of policy inaction (a draft budget is to be presented to parliament at the end of September), will for the first time in over a decade sensitize international investors to the credit risk inherent in government balance sheets. What is intimidating is that here France is in good company, most of the major economies, China, Japan, the UK and the US are as indebted as it is.  

Everything is Fine

On September 16, 1992, the British pound was ejected from the rigid European Exchange Rate Mechanism (ERM) system that it had joined in 1990.  In the ERM, the pound was linked to the Deutsche Mark but effectively at too high a valuation, making it uncompetitive. A few days later, Chancellor Norman Lamont tried to sound upbeat, telling journalists that ‘My wife said she had never heard me sing in my bath before,”, suggesting that he was happy to be rid of the ERM. This characteristic gaffe by Lamont was badly received at a time when British industry and households faced a sharp rise in interest rates.   

The pound’s exit from the ERM came after painful interest rate hikes (from 10% to 15% in one day) and massive intervention from the Bank of England on one side of the foreign exchange market. On the other side, famously, was the speculator George Soros, who ‘broke the pound’ by selling billions of pounds in the expectation of a devaluation. At the time, a youngish Scott Bessent worked in Soros’ Quantum Fund. Today, as US Treasury Secretary, Bessent is having his ‘singing in the bath moment’.   

Bessent has made two interventions in markets in the past month. The first, a historic joint move (the last one was in 1998) with the Japanese authorities to boost the yen. The involvement of the Treasury ensured that Japan was able to buy yen without selling Treasuries, which would have pushed US yields up. In that context, Bessent’s second intervention was a promise to effectively sell short duration bonds, and with the proceeds buy long duration ones, the intention being to push down long-term yields.   
  

Bessent’s moves were greeted with puzzlement and some disdain in markets. Interventions in markets are rare, normally occuring when something is broken or about to break. When they do occur, they need to be large (almost unlimited) to have credibility. Mario Draghi’s announcement that the ECB ‘would do what it takes…and believe me it will be enough’ is the best example. Thus, the Treasury Secretary’s interventions give the impression that something is not quite right, and in this regard, at least three problematic issues are raised.   

The first is that Bessent has announced the arrival of a debt crisis, or rather a debt purgatory, a long period where indebtedness weighs on government policy, markets, and geopolitics. The bond market intervention coincided with America’s debt burden topping the USD 40 trillion mark, and the Treasury Secretary has simply succeeded in drawing greater attention to this.   

Markets registered this in May when long dated (30-year) bond yields on US, UK and Japanese debt hit levels not seen since before the global financial crisis. Bessent’s intervention shows that governments are now feeling the financial pain associated with this rise in yields and are starting to worry about how to curb it. A particular problem for the US, is that a mixture of geopolitics and AI driven debt issuance, mean that there are fewer natural or passive buyers of its debt.   

The second element of note in Bessent’s actions is that they betray a philosophy across the Trump administration that is intensely focused on asset prices to the detriment of economic policy. The president’s active stock trading and public promotion of stock trades, billion-dollar forays into cryptocurrencies, and attempts to shepherd the oil price through social media are all part of this. At the same time, the US has a historically enormous budget deficit, which the rating agency Fitch expects to surpass 7%. In the past a deficit of such magnitude would only occur during a deep recession or financial crisis.   

Today, in the context of a record high stock market, and an AI boom, it is a dangerous anomaly. Should something go wrong to pitch the US into a recession, there is no fiscal cushion. Bessent has done nothing to reduce the deficit and his tinkering in the bond market shows that the deficit is not his priority.   

Thirdly, the bond market intervention is ill timed because the other ‘wing’ of American financial policy, the Federal Reserve, has a new chief, Kevin Warsh, also a former hedge fund manager. Warsh has a preference for a Fed that communicates less to markets, but he has so far not communicated well. Markets are unsure of his stance on inflation. The added complication is that Warsh prefers a more spartan Fed, one that is less active in bond markets, so the Treasury intervention is a contradiction of this. The other concern is that the Fed begins to suffer from fiscal dominance, which in simple terms means that in making policy, it is looking over its shoulder at the actions of the Treasury, and the sentiment in a wobbly bond market.   

With markets still focused on AI, Bessent has unwittingly opened up a macro ‘battle’, which the bond market will surely win.  

Have a great week ahead, Mike   

Bezzle Bonds


In my summer reading note (‘A Good Read’) an important omission was a couple of books by the celebrated economist JK Galbraith, the ‘Affluent Society’ which is relevant to the many economies struggling with low growth (e.g. UK, Germany), and ‘The Great Crash’, a text that will surely come in handy in the next twelve months.   

In this book, Galbraith introduces the term ‘bezzle’ by which he means the rise in fraudulent financial activity as an investment bubble gathers momentum. A slightly different version of this is the rise of what we might call ‘non-traditional’ or opaque forms of financing as the asset bubble gathers pace.   

One nuance of the bezzle, is that there is a moment of suspended financial animation, where the investor in the ‘bezzle’ feels rich, thinks he/she is a financial genius and at the same time the bezzle premium starts to accrue to the architect of the ’bezzle’. Falling economic activity and asset prices bring home the truth of the ‘bezzle’ to the investor.   

Last week’s note on the intense financialization of the South Korean stock market gave a taste of the giddiness that is building around the AI capital expenditure boom. In this context, investment products, such as leveraged exchange traded funds and ‘single-deal’ special purpose investment vehicles in IPOs like SpaceX are ‘bezzle-like’, and it might be argued that new AI startups that raise capital at a high valuation are also bezzles, if not simply hubristic.    

Now, activity in the bond markets and private lending segment is beginning to acquire a ‘bezzle’ premium. For example, last week six of the largest banks and private equity houses announced the creation of a USD 500bn ‘pool of capital’ for Nvidia, to facilitate the buildout of its AI infrastructure. The details of the deal are complex to say the least. This financing package will be considered ‘off balance sheet’, so it won’t immediately show up in Nvidia’s balance sheet, but it will bind the financial and AI industries more closely together (note that a chapter in the Galbraith book has the ironic title ‘In Goldman, Sachs we trust’).   

What is interesting is that bond markets are starting to react. Bonds issued by the large AI firms, or ‘hyperscalers’, are beginning to trade at a higher yield, reflecting the market view that they are increasingly risky. For instance, spreads on the index of hyperscaler bonds are now nearly double what they were at the start of the year, and it is much the same for credit default swaps.   

This is important in at least two respects. First, it signals that individually some of the hyperscalers (META and Oracle are often mentioned) are running down their cashflow rapidly and building up debt just as quickly. Second, the corporate sector is becoming indebted again (from modest levels), under the spell of AI infrastructure build.   

This is concerning as we look towards 2028 (when in my view the AI capital expenditure boom judders to a halt) because public debt levels are already considerable, in fact they have never been higher across the major economies. To that end, public debt markets are also beginning to price in a riskier outlook (long dated bond yields in the UK, South Korea, Japan and the US are at or close to multi-decade highs). Rising real yields (inflation adjusted) tend to be a more cautious signal for markets. Equity markets appear not to notice, or care, but other asset classes like foreign exchange are also signalling trouble in the engine room (the joint US-Japanese intervention in the yen was a case in point).   

The net economic effect is a sort of balance sheet ‘bezzle’, to stretch the analogy. In the US, households have never been more exposed to the equity market, and its rise is producing a marked wealth effect. Based on long run valuations, this wealth effect may be close to peaking though the psychic wealth effect remains strong. On the other side of the balance sheet, government debt continues to grow – one third of all the debt that has been issued by the US has come during the Trump administrations, and corporate debt is edging up as AI infrastructure spending gathers steam.   

Have a great week ahead, Mike

KOSPI Chaos

Apocalyptic stories are emerging of how retail investors in South Korea have made, and then quickly destroyed fortunes in the country’s stock market boom and bust and, we may soon learn that institutional investors, trading firms and banks have been damaged by the fallout. Korea’s Kospi index, which more than doubled from the end of 2025 to its mid-June peak, has collapsed by over 40% since then, with a one-day bounce of 18% at the end of last week.

The index has become an economic absurdity and its volatility (VKOSPI index) is greater than during any of the financial and economic crises of the past thirty years, the Asian crisis of the late 1990s included. There will be considerable damage to the South Korean economy, but so far, unlike the Asian crisis, there is relatively modest contagion across other markets (despite South Korea having rocketed into the top six equity markets in the world).

The absence of broad contagion is not an ‘all clear’ signal. Rather, South Korea is the latest, lurid event in an epidemic of speculation across the world, that is built on the financialization of real economy companies, assets and technologies. While South Korea’s largest technology firms, Samsung and SK Hynix, have become key elements in the AI supply chain thematic (specifically for computer memory), their performance has been wildly exaggerated by financial engineering.

Brokers have created leveraged single stock exchange traded funds on these firms and others, and in recent weeks, trading volume in these financial products has outstripped volume in the underlying stocks by a factor of four times. Option trading volume in Korea has exploded, as has the creation of warrants and structured products, again based largely on the memory stocks. Now, some 3x leveraged Exchange Traded Funds (ETFs) are down between 80 to 95% from their recent peaks. Of course, the majority of trading activity has come from retail investors in Korea, many of whom have used margin debt.

This might all be a bit of emerging market fun were it not for the fact that South Korea is emblematic of the global investment ecosystem, which is driven by the logic of AI capital expenditure but built on the increasingly wobbly foundation of financial engineering. As an illustration, LongView Economics, the independent strategy house, has constructed a ‘Speculative Fervour Index’, based on leveraged ETF activity, and it has risen sharply in the past year, coinciding with an all-time high in US household ownership of equities.

From that vantage point there are at least three serious policy concerns for the US and for American retail investors, if they choose to listen.

The first is a repeated transfer of risk from institutions to retail investors. Semiconductors was just the latest episode, following the SpaceX IPO and the rise and fall of silver and gold earlier this year. The day retail investors stop believing they can beat the market, they will be furious. US households have never owned more equities, wealth per adult has never been as high in America, and wealth inequality in the US is straining historical comparisons. Repeated shocks to households will soon have economic and political effects.

The second effect is the relation between investment and the economy. In an era where Carlota Perez’s (author of ‘Technological Revolutions and Financial Capital’) concept of ‘production capital’ is gaining traction, and where the rebuilding of industrial capacity in the US and EU is a necessity, the risk is that financially engineered investment instruments squander capital and misdirect it from economically meaningful investment projects. High stock market valuations may convince politicians that everyone is getting rich, but there is a serial misallocation of capital occurring before them.

This leads to my third point, which is the role of policy makers, central bankers and regulators. It used to be the case that market stability was a concern for regulators and central bankers, the South Korean authorities have been late to the scene of the fire. In the increasingly ‘regulation-lite’ environment of Wall St., the dominance of financial engineering (there are more ETFs than stocks now and option trading volumes continue to surge), the risk of sporadic volatility events, and, at some stage, a much greater unwind. It should also be a concern for Kevin Warsh, and this is just one topic he needs to be more forthright on. 

For their part, US investors have carried on where the Koreans have left off. In the past three trading sessions, options trading volumes have spiked, driving equities higher. A volatility ‘event’ may not be far off.

Have a great week ahead, Mike  

Modern Times

On May 15, 1932, there was an attempted coup d’etat in Japan, led by a militant, nationalistic faction in the Imperial Army. The principal victim was the Japanese Prime Minister, Inukai Tsuyoshi. The perpetrators of the coup were given relatively light prison sentences, a pointer to the less democratic and belligerent Japan that would soon follow.

The bizarre element of the coup, which fortunately did not succeed, was a plan to murder the actor Charlie Chaplin. The thinking was that such a deed would incite popular fury in the US, and thus lead to war, in which Japan would prevail. At the time of the coup, Chaplin was watching a sumo wrestling match with the Prime Minister’s son, and thereby escaped the assassins.

This was more than lucky and in many ways Chaplin’s film The Great Dictator is a fine riposte to the destructive nationalism and totalitarianism that took hold across the world from the mid 1930’s. It is a film that still resonates today in our world of ‘predators’.

While our view of Japan today is of a placid, highly civilized country, its history in the past two centuries is a reminder of the pitfalls of isolationism, nationalism and war – concerns that are now echoing louder across the international political economy debate. It should be said at the same time that the post second world war relationship between the US and Japan is a good example of how two feuding countries can come together (Al Alletzhauser’s ‘House of Nomura’ is good on this topic).

Yet, such was Japan’s economic rebound after the second world war that America feared the rise of Japan as it now does China, and fans of economic history may know that during the 1980’s and 1990’s Donald Trump was an eminent Japan-trade basher. For instance, the April 13 1987 cover of Time magazine carried an image of Uncle Sam pitted against a sumo wrestler under the banner ‘Trade Wars – the US gets tough with Japan’ (the stock market crashed five months later).

Now, following decades lost to the after-effects of its economic crisis, Japan is undergoing an awakening, spearheaded by the historic election of the first female prime minister of Japan, Sanae Takaichi. This awakening takes different forms, a more assertive diplomatic stance on China, a ramping up of defence spending amidst greater public comfort with the idea of Japan as a budding military power. Also, Japan’s government is ambitious for its economy and has announced a record state budget of 122 trillion yen (over Eur 600 bn), and Japanese firms like Softbank are in the vanguard of the AI boom.

There are two other financial aspects of this awakening. In an attempt to revitalize the Japanese economy, the Bank of Japan had kept interest rates at or below zero for some time. It has abandoned that policy recently and with both growth and inflation picking up, bond yields have surged. For much of the last fifteen years, the ten-year bond yield in Japan has been well below 1%, but in 2024-25 normalised toward the 1.5-2% range, and is now 2.7%, whilst the longer term 30-year bond yield is 3.95%.

As one of the world’s most indebted countries (Japan’s headline public debt to GDP ratio is well over 200% according to the IMF), the effect of this is that fiscal policy is increasingly smothered by the effect of interest payments on that debt, and policy is trapped between trying to grow the economy, control inflation and not upset the bond market.

Equally the yen is grabbing attention, falling to a forty-year low this week. Indeed, it might well be lower, but traders are wary of a market intervention by the Japanese authorities. There are several factors driving this, the hedging of foreign exchange risk by investors buying Japanese assets, real interest rate differentials, and worries over the effects of expansionary fiscal policy. A costly bout of yen intervention might be close.

As Japan’s asset prices hit records for largely the wrong reasons, it serves as a reminder that many large indebted economies exist on a financial tightrope between growth and calamity. Britain is the most prominent example, but Japan is a more systematic case and over the summer could be the source of a market wobble, if not outright crisis as bond market sell-offs become more common in our ‘age of debt’.

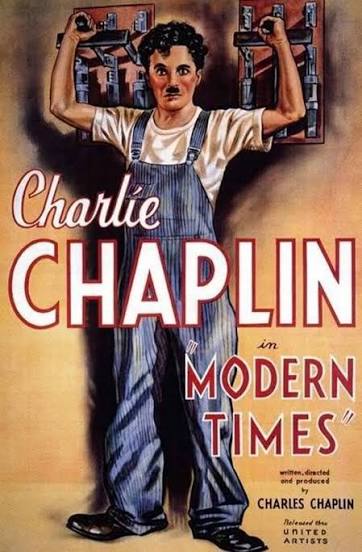
It’s all enough to make me think of Charlie Chaplin’s depression era film Modern Times.

Have a great week ahead, Mike

A Bit of Reality

The advent of the Kevin Warsh Federal Reserve with its first meeting last Wednesday, very likely heralds a new departure in American central banking. The Warsh Fed will likely be less effusive in its communication (notably there will be less public defending why the Fed doesn’t hit its forecast levels of rates and inflation), will be more closely coordinated with the Treasury, and if the track record of the new governor is to be believed, will be much more reluctant to use the balance sheet of the central bank to support markets and the animal spirits of the economy. The real test of this will be next economic crisis, potentially a public debt crisis that starts in the next couple of years.

In the medium term, the backdrop to the Warsh Fed will likely be characterised by tighter liquidity conditions. Warsh will likely slow the Fed’s reserve accumulation program, equity issuance by tech firms, IPOs, new bond issuance (again, for AI infrastructure) will also mop up market liquidity and following a bout of bond retirement in the second quarter owing to a bumper tax take, the US Treasury will increase debt issuance from the end of June onwards (up to USD 600bn in Q3).

So broadly speaking from a ‘plumbing’ view of markets, there will be less liquidity shooting around the pipelines of markets. Ordinarily, this is not great news for risky assets like equities, especially with valuations at the very top of 100-year ranges. However, the asset class that intrigues me, is bitcoin, already a significant underperformer this year. The mystery being that bitcoin has yet to reveal its true identity as an asset class, let alone a money.

Bitcoin was established in the aftermath of the global financial crisis, as an alternative to paper money and the institutional framework around that money (i.e. the Fed and the ECB), but has failed in this aim. Bitcoin is not a money. It is simply far too volatile to act as a reliable store of value or basis for payment. Also, the technology associated with cryptocurrencies is also complex enough to dissuade most households from using them.

As a case in point, I can recall that in bitcoin’s early days (2016), train stations in Switzerland’s ‘Crypto Valley’ had a facility to exchange swiss francs for bitcoin, and the canton accepted bitcoin as payment for taxes and services. But transaction fees were very high, and this experiment hasn’t caught on. In fact, only some 0.1% of tax settlements in the canton of Zug were paid in bitcoin.

While the Swiss authorities were happy to give bitcoin the benefit of the doubt, most institutions in the old-finance world, primarily central banks who plan their own digital currencies, have an incentive for it not to succeed, and famously in 2021 Christine Lagarde referred to bitcoin’s ‘funny business’.

Reflecting this, the weakness of bitcoin has not been the technology, but rather the infrastructure around it, and the people who have used it as a means of payment. In the past five years, a good number of exchanges (in Asia) and brokers have collapsed or been shut down, and the entry and exit points to the crypto world are under examination from tax authorities. Also the anthropology and sociology of those who populate the crypto world is crucial to how these assets behave and subsequently to their risk characteristics. In this light the, fact that the biggest holder of bitcoins is apparently the FBI says a lot.

Bitcoin, and the broader crypto world, now face two new competitors of sorts. One is the growth of stablecoins (which are based on the Ethereum blockchain), which may facilitate ‘grey’ economy transactions far more efficiently than bitcoin. The other is AI, whose claim on the electricity and energy sources of the world, makes the production of bitcoin more expensive. Lurking in the future is quantum technology, which some fear could break the bitcoin protocol.

So, bitcoin is far away from meeting the objectives of a ‘money’, and in my view is a ‘tulip’, a speculative, trading asset. It also seems to me that many people are increasingly happy with bitcoin being assigned this role, and much of the interest and eco-system that is developing around it underpins the role of bitcoin as a speculative asset rather than as a bona fide currency.

As such, this points to bitcoin and crypto currencies being ushered into the corner of eclectic trading assets – though less of an experience than horse racing, with none of the aesthetic bonus of art and not quite the fun of collecting wine.

These assets tend, in my experience, to be driven by waves of liquidity, and surges in wealth, as opposed to more fundamental factors. Thus, with the prospect of weaker liquidity ahead, bitcoin is in for a test. It has been claimed that bitcoin is a safe haven, or digital gold, but in general its tendency is to weaken as macro uncertainty rises. It might be the first victim of the Warsh era.

Have a great week ahead, Mike

AI as an asset class

A very early career memory of mine came in late 1999 when the UBS investment bank took the team of analysts covering the staid Paper & Packaging team and re-directed them to become the ‘dot.com’ team. This I reckon came about six months before the peak of the ‘dot.com’ bubble and, I am now wondering if investment banks are channeling resources into AI banking teams (surely AI can do the work!). If so, it would be proof of the idea that AI is everywhere, from the Mythos breakthrough we wrote about a few weeks ago to, with good timing the thoughtful note, Magnifica Humanitas, from Pope Leo XIV on how AI should be deployed.

Nowhere is the sense that AI is everywhere more true than in finance. According to Pitchbook, 45% of all American unicorns (venture-backed companies with a valuation above USD 1bn) are AI-driven, not bad for a technology that, to public eyes, barely existed three years ago. In more detail, two earlier venture-backed successes, Bytedance (i.e. TikTok) and Uber had been established for 80 months when they launched their first products. OpenAI and Anthropic have done so after 30 months, and each is now worth close to USD 1 trn. Equally, illustrating the link between investor exuberance and AI, the FT recently estimated that two-thirds of the value of SpaceX is attributable to investments made in the company in the six months since December 2025.

When this trio of AI firms lists on the stock market, revised index inclusion rules will add their weight to the already substantial 44% representation of technology stocks in the major indices. To that end, AI is no longer a market theme or fad, but is becoming an asset class in its own right.

One of the factors that distinguishes a genuine asset class from a market theme or fad is the presence of a transformative technology, with a lasting economic impact. In the context of an otherwise pedestrian US economy, AI capital expenditure is the dominant growth driver and in the last year, expenditure on data centres in the US hit USD 1 trillion.

A comprehensive study from Stanford’s Forecasting Research Institute (March 2026) compared GDP forecasts from different types of forecasters – economists in the private sector, academics, AI experts and the general public. Unsurprisingly, those closest to the AI industry tended to have the highest GDP forecasts, while academics were more grounded. On balance though, there is a consensus view that AI will lift the trend rate of growth in the US.

There are also increasingly varied ways to invest in AI. An AI-centric portfolio can now span private equity, venture capital, infrastructure (clean energy for data centres), real estate (data centres), currencies such as the Korean won, corporate bonds (Amazon, Meta, Oracle and Alphabet have issued nearly USD 150bn in bonds this year) and private credit. Indeed, AI-related private credit investments are expected to grow by over USD 1.5 trn in the next two years. While there is already a rich mix of AI-centric asset classes, the correlations between them remain high, limiting the diversification benefit.

In addition to investment banks committing resource to AI-driven deals, another hint that AI is an emerging asset class is that it has its own distinctive mode of corporate governance – strong-willed founders who monopolise voting rights, enormous pay packets and neutered boards. This concentration of control is likely to prove one of the structural vulnerabilities of the AI complex as scrutiny from regulators and institutional investors intensifies.

Given the scale of AI’s footprint across markets, one of the essential tasks for investors will be to identify assets uncorrelated with AI (e.g. luxury goods, food), as well as hedges on AI assets. And, as the suspected AI bubble grows in value, investment managers will have to find ways of protecting portfolios against sharp reversals in AI valuations.

The investment dimension of the AI boom carries particular urgency. Given the risk that AI (as per Mythos) creates potentially existential security and economic risks, and could disrupt labour markets, there is a strategic need for pension funds and sovereign wealth funds to have exposure to the economic benefits of AI. As it stands, the risk is that billions of people will have their lives and livelihoods changed by AI, but the benefits accrue to only a narrow group of investors and executives. In that regard, the advent of AI as an asset class gives individuals, countries and investment funds a means of participating in the upside of the AI boom.

The one formidable obstacle investors will have to navigate is the sense that we are in the thick of an AI bubble. Already long-run valuation measures –  such as the ratio of market price to long-run earnings (the ‘Shiller P/E’), or the ratio of the value of the US stock market to GDP – are testing all-time highs, at levels not seen since 1929 and 2000. In this way, AI is truly everywhere, in our savings, investments and pensions, and that will be a risk.

To return to my first point on the switching of analyst roles. A couple of brokerages have, according to the Wall Street Journal’s China correspondent, dropped coverage of Chinese consumer stocks because of the weak outlook for spending. It might be the next trend to watch.

Have a great week ahead, Mike 

Lost at Sea

As a child I was fascinated and terrified by tales of the Bermuda Triangle, an area between Florida, Puerto Rico and Bermuda where ships and planes disappeared without warning, allegedly. Legend had it that a mysterious magnetic field around the Sargasso Sea drew vessels to perdition, or that even darker forces were behind the disappearance of the crew of the Mary Celeste.

Without stretching the analogy too far, my feeling is that financial markets have entered a logical Bermuda Triangle, or even Trilemma. Data, models, rules and indicators go in, but come out logically impaired. In particular, there is an unreal sense from at least three asset classes that are at historically extreme levels, each apparently contradicting the other. They cannot all be right.

In one corner, the US has, for the first time since 2007, issued long-term debt (30 years maturity) at a yield of 5%. Then, US stock market valuations are at an all-time high since 1929 and, as we stressed in last week’s note, semiconductor stocks are in a speculative frenzy. In another corner of the triangle, oil prices are pushing the highs of the last two decades.

This trio of market signals leaves investing logic in a grey zone — a Bermuda Triangle-like make-believe world. This stretched logic suggests that the prosperity and productivity of AI-related capital expenditure will rescue the world from both high inflation and a debt crisis, and will also prove powerful enough to compensate for the effects of a momentary energy crisis. I am not sure.

The confluence of these three indicators is interesting because each one points to a long-term trend that investors and policymakers cannot ignore, but equally, each one rests on a short-run vulnerability.

Rising bond yields in Europe, the UK, Japan and the US are an early warning of a debt crisis, or debt purgatory, to come. In the very short term, they signal that inflation is creeping higher whilst a number of policymakers — notably on the Fed’s FOMC — appear complacent about this development.

Equities are trading at record high levels and valuations, mostly because earnings and business cycles are strong. But a very small number of stocks has pushed the market higher, caused in part by the fact that sectors like semiconductors are heavily financialised. What I mean by this is that the deployment of exchange-traded funds and options has surcharged the prices of semiconductor stocks, and likely driven them well above long-term fundamental valuations.

In my view, Intel’s ability to treble in value since the end of March (from USD 41 to USD 129 last week) has less to do with the fundamentals of the company, and more to do with speculation. In support of this, a recent Goldman Sachs note shows that retail investors now account for around 20% of US stock market trading.

Energy prices remind us that in a multipolar world, commodities — or rather their supply and refinement — acquire a premium, and that a number of countries will have to address shortcomings in industrial supply chains. For example, last week Willie Walsh, the former airline chief executive, warned that the UK has scant jet fuel refining capacity. As such, energy infrastructure will be an area for future investment.

In the short term, however, supply pressure may be more acute: oil inventories are being drawn sharply lower. Unless there is a full and speedy resolution to the Iran War, estimates from JP Morgan point to world oil inventories dropping to 6.8 billion barrels by September — just enough to keep refineries operating worldwide.

So, like the Sargasso Sea, market compasses are spinning in different directions, and it is difficult to discern a clear narrative. The confusion arises from the changing geopolitical nature of the world, the fast shift in industrial structure away from ‘bits’ and towards ‘atoms’, shortages of refined oil and compute, and the intense financialisation of specialised sub-industries such as semiconductors and commodities.

Given the disagreement between markets, the obvious question is: which one is right? A ‘two-handed’ economist might argue that the stock, commodity and bond markets are all correct, but on different time frames.

In my experience, the bond market is the most consequential, because when it worries, it imposes a cost on other markets and on political actors. The overused but apt quote from President Clinton’s adviser James Carville in the mid-1990s captures it well: “I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.”

So, the ‘market triangle’ or trilemma is resolved by bonds showing their displeasure at high oil and inflation, slowing the economy and walloping the over-bought sections of the stock market.

From a policy angle, bond markets are highlighting the urgent need for policymakers to calm inflation — through rate rises from central banks, and an early test for incoming Fed Chair Kevin Warsh — for governments to reduce debt, and for greater policy clarity in countries like the UK. The silver lining is that credit markets are so far well behaved, signalling that the healthy business cycle should allow for these policy actions to be made now, before it is too late.

Have a great week ahead,  Mike