

Processing…
Success! You're on the list.
Whoops! There was an error and we couldn't process your subscription. Please reload the page and try again.
One of the implications of the overwhelming swing to the Democrats in the mid-term elections is the change in the nature of the discourse on policy and amongst many interventions, one I found curious is the way Democrats like Gina Hinojosa, the coming governor of Texas have used the term populism, which they appear to mean the struggle of the people against the (corrupt) elites.
In contrast, I associate populism with the easy promises that politicians on all sides of the political spectrum make habitually. For instance, the economic programs of the far left and far right in France are cases in point. In this context, populism is encapsulated in a quote from the former Argentine president Juan Peron, where he remarked ‘“My dear friend: give the people, especially the workers, all that is possible, . . . there is nothing more elastic than the economy, which everyone fears so much because no one understands it.”
The problem, for those who have either a redistributive or overgenerous conception of populism, is that the elastic of the economy, to borrow Peron’s term, is about to snap, in a most unfortunate way. As we have noted many times in these pages, debt levels for pretty much all the major economies are at record highs (world debt to GDP has never been higher) and oddly given the world economy is still in an expansion phase, budget deficits are at levels (5-6% of GDP) that historically have only occurred in the context of a bad recession or war.
There is no money left. Normally, the blame for this might fall on the men (and women) in grey suits, the finance ministers and central bankers. Finance ministers have not been able to say no, and it is hard to think of a country where the national purse is held by a fiscal hawk (Italian, Swiss and Canadian finance ministers stand out for a modicum of fiscal discipline).
Central bankers may also be complicit because they have convinced markets, finance ministers and the general public that they will deploy their central bank balance sheets if there is a whiff of economic trouble. Come the next financial crisis, we can blame the men and women in grey suits.
But, the public are also to blame. There are no votes for austerity and debt reduction.
Few candidates in the US midterms dared to campaign on the need to reduce spending, the Labour government dare not make a significant dent in welfare spending (last week former minister Alan Milburn launched his report on youth benefits) and in France, voters allow themselves to be seduced by the fantasy economics of the left and right.
Opinions polls across the world suggest that the public wants ‘to have its cake and to eat it too’. In France, polls (from Elabe and Fabre) show over 80% of respondents ae concerned about the national debt, but equally against all measures that might reduce it, like pension reform and spending cuts. In the UK, YouGov and British Social Attitudes surveys show no tilt towards ‘cutting spending and raising taxes’. In the US, there is a slowly emerging consensus against further cuts to social welfare spending, and in favour of higher taxes on top earners. Overall, the public view seems to be ‘debt needs to be reduced, but not through me’.
What is also largely absent from public debate is any real sense that the public grasps the scale of the financial burden landing on taxpayers, on those who rely on public services, or even on the wealthy. Echoing Peron’s comment that ‘no-one understands it (the economy)’, there is a growing literature that suggests people are either genuinely ignorant of, or choose to turn a blind eye to, the consequences of high debt.
Francesco Bianchi of Johns Hopkins, together with Era Dabla-Norris and Salma Khalid of the IMF, used survey data on 27,000 individuals across 13 countries to reach a fairly gloomy conclusion: individuals consistently underestimate debt levels in high-debt countries, and tend to believe fiscal adjustment will fall disproportionately on them personally; only a small group of older individuals holding financial assets shows a meaningfully better grasp of the fiscal situation. Broadly in the West, not to mention countries like China, people have only a weak grasp of the links between taxation, deficits, spending and debt. But, we might say the same of many finance ministers.
One reason that budget deficits have grown so much, with the connivance of the public, is that they have been financed by higher debt issuance, as opposed to tax hikes. The public experiences debt quite differently from taxation, taxes are visible and painful, so voters pay close attention to them – the public tracks the cost and duration of a conflict, for instance, more closely when it is financed through taxation. Debt financing severs that relationship almost entirely, which is precisely why it is the easier, more popular route for governments to choose.
In short, the public in large, indebted economies are unprepared for the long period of fiscal adjustment that will follow debt convulsions. Greece, Ireland and Spain have run this gamut. With much of the Western world already in a democratic recession, to use political scientist Larry Diamond’s term, the political consequences of debt can be severe.
In the aftermath of a debt crisis, there is often a lurch away from established parties, towards political extremes. The difference this time is that in the US and France at least, the populists may be the ones to strand their countries on the fiscal rocks, and the public will be complicit in this wayward journey.
Have a great week ahead, Mike
At a time when the runners and riders of the French presidential campaign seem largely like a lacklustre lot, spare a thought for Roland Dumas, who died just over two years ago at the ripe age of 101. Dumas was a dashing figure in French politics and was Francois Mitterand’s point man on foreign affairs for close to seven years and directed French foreign policy through the fall of Communism and events like the first Gulf War.
Dumas, however, is also famous for his affair with Christine Deviers-Joncour whilst he was foreign minister and when she was in the highly lucrative pay of Elf, the oil company. Once news of the affair and Joncour’s arrangement with Elf broke in 1999, Dumas resigned as head of the Constitutional Court, and Joncour’s account of the adventure was famously published under the title ‘La Putain de la Republique’.
Jensen Huang, who resigned as Nvidia’s chief executive on Thursday, is not quite as dashing as Dumas, though certainly a lot richer. His affair with Alice Huang, whom US intelligence officials reportedly suspect of working for the Chinese intelligence services, has, however, proved far more consequential than the Elf case. The scandal has now cost Huang his job at the helm of the chipmaking giant he co-founded, with Nvidia appointing its long-serving chief financial officer, Colette Kress, as interim chief executive.
Readers who were expecting me to devote this note to tales of mistresses and honeytraps will be disappointed, because there are several threads to the Nvidia story that are worth focusing on, notably the implications for geopolitics, the operation of the White House, and the emerging Great Game between the West and the countries of the Shanghai Cooperation Organisation (SCO). In a note last year, I describe the shadow wars these countries are mounting.
This story is emblematic of the AI bubble, and more generally of a world in geopolitical disorder. In particular, questions will be raised as to why intelligence from US agencies was not acted on more urgently by the Trump administration. More tellingly, Nvidia has apparently been caught napping, and here there are at least three strands worth examining.
In May we wrote a note (‘Goodbye Governance’) on the peculiar, inferior corporate governance model that characterises the fast-growing AI giants, and the ownership structure of Anthropic that is evident in its forthcoming IPO prospectus is a case in point. Compared to the majority of the staid firms in the S&P 500 index, the AI companies are evolving quickly and may not have well established governance structures and norms (Jensen Huang had 50 different direct reports apparently). In many cases, founders tend to dominate the firm’s strategy and often have special voting rights (not the case for Nvidia). As such, the mechanisms to detect and challenge untoward behaviour may not have been well thought through.
One failing of Nvidia is the lack of a well thought through succession strategy, a weakness now exposed by Huang’s abrupt resignation. This succession process, and the task of mapping how a founder or long-running CEO has ‘wired’ a firm, is a significant though underestimated problem for family led middle sized firms.
In this context, a very interesting development in the corporate sector is the emergence of corporate intelligence teams, though in some cases the likes of Total Elf have been at this game for some time (we recently highlighted a ranking of the capability of European spy agencies, ‘Spies Like Us’). An authority on this field is Lewis Sage-Passant, and I can recommend his books (such as ‘Beyond States and Spies’).
Mostly corporate intelligence agencies are defensive – they exist to protect against the theft of intellectual property, warn employees from being honey trapped on business trips, block cyber attacks and other electronic assaults and steer employee safety in dangerous locations. In a few cases, corporate intelligence teams take a more aggressive role, but to my limited understanding, they are defensive and collaborate with similar businesses in friendly economies to block the activities of common enemies (i.e. the members of the SCO notably). There is also a growing niche digital sector that helps companies identify the true background of business counterparts in ‘emerging’ economies.
One of these is the MSS, China’s massive spy agency, that not only employs tens of thousands of spies, but co-opts many other Chinese citizens to gather grains of intelligence around the world. Indeed, some will claim that the reach of the MSS extends through European and American universities, increasingly through international institutions like UNESCO and the UN. A great spy game is now truly underway, the likes of which John Buchan would be proud.
Such is the scale of the MSS, and their reach across cities like New York, that it is physically impossible for the FBI to keep tabs on the myriad of operations. The allegation against Alice Huang marks the coming out of the MSS in the Western public view and will strengthen the hand of the China hawks in the Trump cabinet. It may well also tighten the surveillance of the business relationships of the Trump clan and their associates, especially so in the light of the mid-term election results. The credibility of the White House, Jensen Huang and Nvidia are all damaged.
As a final thought, the incident is another proof point in the ‘end of globalization’ thesis and the onset of a world of strategic competition where sensitive technologies are sought after. Chris Miller’s book ‘Chip War’ was an excellent example of the ways in which supply chains and prized innovation have become weaponised.
Have a great week ahead, Mike
In Cork last week, I looked across the River Lee from the vantage point of the Marina, and I thought of the first line in Alexis de Tocqueville’s account of my home city, written in 1835 (by his associate Gustave de Beaumont), ‘the entry into Cork is very fine’. Very sadly, much of the rest of Tocqueville’s account of Cork and Ireland describes great poverty, inequality and injustice. Back then, Tocqueville was a well-known, political thinker in Europe, famous for his work (with de Beaumont) ‘Democracy in America’, based on their visit to the United States in 1831, ostensibly to study the prison system, but that became a broader, insightful commentary on American society and democracy.
Today, ‘Democracy in America’ is still regarded as one of the most pertinent accounts of American public life. He observed America’s march towards democracy, and potential for this idea to spread to other countries, the beginnings of severe inequality and exclusion in American society, the power that religion had over the populace, a strong sense of the individual coupled with a belief in local democracy and activism. Tocqueville also flagged the risks to democracy from despotism and smothering bureaucracy (‘a tutelary power’). All of those threads are current today, and many of them have been manifest in the midterm elections.
We previewed the elections two weeks ago (Midway, the End or the Beginning), and by most benchmarks the result is startling for the magnitude of the reversal for Donald Trump and the Republicans. Multiple, historic records were set, for instance the first female, native American (de Tocqueville mentioned their plight) governor was elected in New Mexico, and a raft of female former military officers won elections, some like Vice Admiral Nancy Lacore had been fired by Pete Hegseth.
What is clear is that many Americans, whom we might describe as falling into the early socio-economic cracks described by de Tocqueville, and whose state of mind is captured in JD Vance’s book ‘Hill Billy Elegy’ have come to the slow but firm realization that Donald Trump is not the man to address the long-running concerns they have over the cost of living, wealth inequality and America’s place in the world.
One of the most interesting diagnoses of this came in a long tweet from the Vice President, in what is surely his first unguarded utterance in over two years. Bluntly he states that the administration needs to end the war on Iran, focus on the cost of living, change its relationship with Israel and put ‘America First’.
Vance must realize that his chances of winning the 2028 presidential campaign are very slim, as are those of Marco Rubio. My sense is that economically astute, experienced policy makers (with military backgrounds) like Mike Pompeo and David McCormack are the kind of candidates the Republicans will gravitate towards.
The Democrats will go from having a poor, unprepared candidate in 2024 to a cast of apparent political geniuses. Jon Ossoff and Pete Buttigieg are two of the leading candidates, as is Gavin Newsom, but my suspicion is that on the road to 2028 the Democrats risk convincing themselves that a woke, leftward tilt is the way forward and thus become irrelevant in the same way the left has done in many European countries. The example they will want to avoid is the landslide win for the Labour Party against the unpopular Tories in 2024, and the ways Labour subsequently neutered itself.
If the 2028 election has now started, many other events will occur quickly. Pete Hegseth might be fired before he is impeached, the boon may be that Trump uses this moment to bring the Iran War to a halt, and that this provides the backdrop for a similar settlement in Ukraine.
Two weeks ago, we suggested that a Democrat majority in the Senate would lead to a shift to bonds and out of AI stocks. This trade has been building for the past two weeks and bond yields have dropped 40 basis points. The consensus view is that many Democrats are against AI, or at least its overlords and owners, and the consequences of its machinery (from data centres to surveillance). It is not clear that Democrats can halt the march of AI capital expenditure, and when they discover that this is the one engine propelling the US economy they may be less critical. But, in certain states like Texas, known for its business-friendly outlook, the new governor (Gina Hinojosa) may try to halt the build of new datacentres, nearly half of which are pitched by ‘first time’ data centres teams. If she does, she might rescue billions in shareholder capital.
Finally, two things surprised me through this campaign. The first is that whilst the cost of living is the top political issue, few politicians have raised the looming catastrophe of America’s financial situation (political ads that mention the budget deficit have been scarce compared to previous elections). A budget deficit of 6% and debt of GDP ratio mean that American politics, like France and the UK, is set to be smothered by the ‘fiscal question’.
Then, to return to the sharp observations of Tocqueville, American democracy still works it seems, but the resolute vote is in sharp contrast to the lack of courage shown by many lawyers, entrepreneurs and business leaders, not to mention Senators, over the past two years. I just wonder why some Americans are so disappointed in their choice of president, they had plenty of warnings.
Have a great week ahead, Mike
Last Wednesday, Andy Burnham’s Chancellor, John Healey delivered his budget, which was a tame affair. Fiscally, the UK is in as bad shape as France, but without the good food, impressive infrastructure and lavish pensions. Though at least it has a ‘keep calm and carry on’ perspective, unlike the anarchy and vandalism that has been visited on French cities. Markets shrugged at the Healey budget, much of which had been signalled in the press and social media, and above all, with very limited fiscal space, he had little scope to do much.
It wasn’t always the case. One of the great tasks of City economists was the parsing of the Budget. Budgets were great set-piece affairs, dramatized by Chancellors like Ken Clarke sipping whiskey as he delivered the Budget. Trolleys of sandwiches (and a few whiskies) would be delivered to economist’s desks as they made sense of the Budget and then transmitted their views to gilt, currency and equity investors, sometimes by fax. The Budget was a frontpage story for nearly all newspapers.
An early, formative career experience of mine was an internship in the City of London, where I sat a few metres away from the office of Gavyn Davies, then (and now) a very prominent economist. He was instrumental behind the scenes, in spurring some of the early policies of the New Labour government of the 1990s, such as the radical move to give the Bank of England its independence. That was a market moving event.
In contrast to the Healey budget, another market moving political event this week was the initial 24% drop (in dollar terms) of the Brazilian stock market in the wake of the surprise victory for ‘Lula’, and the 3% drop in the Tel Aviv stock market following Wednesday morning’s election result.
The latter two events suggest that either investors do a poor job of forecasting elections or more importantly, that politics is ‘back’ as a material factor for market returns. The next test of this will be the US midterms, which we previewed two weeks ago (MidWay), where a strong swing to the Democrats (i.e. Senate majority) may see a correction in AI stocks, crypto and the price of oil (my instinct is that a Democratic Senate would hasten an end to the Iran War, and the White House might be happy with this).
Though it is intuitive that politics and policy will drive markets, especially ‘macro’ assets like currencies and bonds, it has not been the case in the past two decades. First, the period of globalization produced long periods of growth, with generally low inflation and an absence of wars. During this period, politicians were generally well behaved and stuck to the rule of law and world institutions. Market volatility tended to be generated by hubris and excessive leverage.
Second, in the post global financial crisis era, the near permanent application of quantitative easing by central banks dulled the responsiveness of investors to politics and geopolitics, and to a certain extent investors operated under the belief that the market reaction to bad news would be underwritten by central banks. That era is now over. Inflation is back, central banks are raising rates and the world is gripped by several major conflicts, plenty of smaller ones (across Africa) as well as the evolving Russian hybrid war on Europe.
Also, there has been a marked deterioration in the quality of policy making, and a concomitant rise in geopolitical risk. The Economic Uncertainty Index produced by three American economists is off the highs it attained in March ‘25, but still well above its historic average, and other geopolitical risk indicators are extended. In particular the fiscal constraints that most of the major governments face, will increasingly produce popular discontent (in the case of France), or unorthodox policy moves (Donald Trump’s tariff policies). Further, in a world that has gone from ‘open’ trade to a mindset conditioned by ‘sovereignty’ and resource bottlenecks, straightforward conquest is back on the menu of geopolitical strategies (e.g. Venezuela).
My intuition, based on previous research, is that in the expansion phase of the business cycle, company specific factors like earnings matter most to markets, but in downturns, country-specific factors (politics, policymaking) exert a bigger influence. For the time being the world economy is resilient, and in growth mode under the steam of AI led capital expenditure. But a phase of weaker growth and earnings, coupled with higher inflation may well mean that political risk exerts a greater role in asset prices like commodities and bonds, and in some cases asset prices are driving politics.
As we head into 2027, a range of events and assets comes to mind – peace ‘deals’ in Ukraine and Iran would impact energy and bond markets (interestingly Pakistan, Saudi Arabia, Turkey and Iran have held talks in Tehran recently), elections in Spain, possibly Germany and of course France will produce trades in banks and bonds. A ‘black swan’, to misuse Karl Popper’s term, might well be the machinations within the Chinese Communist Party as it tries to manage the ongoing deflation of the property bubble, the impact of this on house prices, and a tax crackdown on overseas assets of wealthy Chinese. This has started to impact the Chinese stock market and may soon rebound on the Communist Party.
Have a great week ahead Mike.
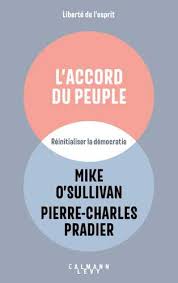
In February 2024 Pierre-Charles Pradier and I launched ‘L’Accord du Peuple’ (Calmann Levy), our argument to bring the apparatus of French democracy closer to the people, and in so doing avoid the stalemates and frictions that seem to convulse France. The book made the case for more participative democracy, greater power for regions, more transparency and accountability of local, regional and national budgets, and we also strayed into the debate on the corrosive influence of social media on politics.
A few months after the publication of the book, Emmanuel Macron’s party was handed a beating in the European elections and in a catastrophic unforced error Macron called a general election, from which he and his many governments have not recovered. During the hasty 2024 election campaign Pierre-Charles and I thought our moment had come but, it seems we had fooled ourselves, there is very little desire in Paris to surrender power to the people.
A lesson, for me at least, is that the roots of governance in France are deep and potentially go back to the medieval period – Paris is the citadel of power, where barons (Edouard Philippe’s ‘Dans L’Ombre’ is worth a read), ‘knights’ and janissaries serve and rise through the system. There is an intense homogeneity across those who populate the system, that is not found in other European countries like Germany. Though, in general as a process, the system works well, it struggles when it is required to change.
To that end, the notion that France is ungovernable (expressed widely in Anglo-Saxon countries) is wrong, it is over governed, and the system of the state excludes most French people. Recent changes to the political system, such as the removal of the ‘double mandate’ that ended a practice where local mayors could also serve as parliamentary deputies, have put more distance between local politics and Paris. Another observation is that France, compared to smaller European countries like Switzerland, Sweden and especially Ireland, is a very low trust country, and this element can make democracy harder to operate.
In that context, protests like the Gilets Jaunes reflected a view that the state is removed from the people. Since then, through the COVID crisis and the Olympic Games, there has been a remarkable degree of calm in public life, which has irregularly been punctuated by outbreaks of vandalism (e.g when PSG won the Champions League). Increasingly, what may once have been political protests, led and managed by unions, are now festivals of wanton violence, of which October 17th is an example. There is still a large cohort of commentators in and beyond France who over analyse and philosophize the reasons behind the vandalism but, there is a growing public consensus that it is reckless, dangerous and damaging to France.
It comes as France has entered a ‘debt purgatory’ (our Barrons article in August set this out), and when the 2027 presidential race is vigorously underway. The seemingly unassailable position of Marine Le Pen reflects both the discontentment of French people with Emmanuel Macron and the ‘establishment’, and relatedly a widespread view that immigration/identity/integration is a political problem that has not been addressed. The strength of this view is such that it ignores Le Pen’s suitability as a candidate, her lack of experience, economic illiteracy and the potential friction that a Le Pen presidency would cause across Europe. Yet, the presidential race is a steeplechase, with plenty of obstacles (recall that this time in 2016 Francois Fillon was the favourite to win the 2017 election).
A Le Pen presidency will surely deepen France’s burgeoning debt crisis, and very likely produce a market event such as a run on the French banks. Such an event may be necessary to convince the French public of the need for drastic reform of their economy. Denial of the extent of the fiscal challenge remains strong.
In this respect, what is striking across the political spectrum in France, is how nearly all of the candidates operate in a restrictive view of the French economy as a redistributive system (tax heavily to spend hugely). This perspective ignores France’s economic strengths in innovation, production and engineering, but also condemns the country to a future of low economic growth. A truly revolutionary, providential candidate, if one is to arrive, would focus more on a complete rewiring of the French economy, though to my earlier point, I suspect that the system may not permit that.
Those commentators looking in at France from afar and drawing the conclusion that the wrecking of the country is yet another expression of French exceptionalism are very wrong. The worrying aspect is that France is simply a showcase to the two problems that beset the world, indebtedness and a crisis of democracy (three is we include the side-effects of climate damage). The US, China, Japan and the UK are as or more indebted than France. Britain has had six prime ministers during the time Emmanuel Macron has been in power. American democracy is faltering, and Washington is dallying with autocracy.
The ways in which individual countries deal with these twin challenges are central to the idea that the world order is in an ‘Interregnum’ phase and will determine the winners and losers of the 21st century.
Have a great week ahead, Mike
America’s midterm elections are not unlike local elections and by-elections in the UK and European elections across the EU – an often-dull event met with low turnout, but that nonetheless provides an important check on public opinion, guards against complacency by the incumbent power and helps to refresh the bloodline of politics (perhaps less so in the gerontocracy of American politics).
In this context, Republicans should bear in mind that in recent years local elections (UK) and EU polls) have proven consequential. An expected poor showing in last May’s local elections was reason enough for the Labour party to jettison Keir Starmer, while Emmanuel Macron’s foolish decision to call a general election following a weak result for his coalition in the 2024 European elections, sapped his government(s) of power and credibility.
In the US, the mid-terms have at times been fateful. In the November 5th, 1946, midterms John F Kennedy, Joe McCarthy and Richard Nixon all entered politics. In an echo of the debate on poverty in San Francisco today, and the Californian billionaire tax, the 1934 California gubernatorial election saw the Democrat Upton Sinclair (he was closer to a Democratic Socialist in today’s terms) launch a campaign entitled ‘End Poverty in California (EPIC)’. Business and landowners didn’t like this, and the movie studio bosses set against him and they spurred an attack campaign against Sinclair using fake newsreels. Upton lost to a colourless Republican in what was likely the first ‘fake news’ political attack campaign, but most certainly not the last.
In three weeks’ time, Americans will vote in a consequential midterm roster of votes. As I write, polls and prediction markets point to the potential for a Democrat upset in the Senate (65% probability). The House of Representatives already appears settled – the Democrats need three more seats for a majority but look like they might take up to ten. In the Senate, polls suggest that the Democrats will hold most of the contested ‘Blue’ states – Jon Ossoff will for example easily win Ohio. Then, it looks likely that we will see upsets in Alaska, Maine, Texas, Ohio and maybe Kansas. Since 1861 there have been 29 Republican Senators representing Kansas and only 3 Democrats, the last being in 1932.
As such, a swing to Democrats in Kansas would be emblematic of a major upset, and here there are many things at stake. The most obvious is that the midterms are a referendum of sorts on President Trump, the economic spillover of his war on Iran, growing financial polarisation and the conduct of politics. A very important consideration in the context of manifest corruption (recall that President Trump has promised USD 5,000 to Americans if his party is successful in the midterms) is the role of the democratic system as a check on executive power, and in this context a resolute vote against the President’s party and its many ill-chosen candidates, should be accepted as a sign that American democracy functions.
The midterms will also prove a steer for the next presidential election. A poor showing for the MAGA Republicans will surely dent the chances of the likes of Marco Rubio and JD Vance in 2028 and encourage the likes of Mike Pompeo and David McCormack. On the other side, if the likes of Abdul El Syed in Michigan are victorious, such a result might embolden the Democrats to present a Democratic Socialist presidential candidate in 2028 (a mistake in my view).
Into 2027, a Democrat held Senate might tilt policy in several ways. First, there may be an attempt to impeach ‘War Secretary’ Hegseth, granted the number of Republican Senators who disdain him and even, a move to impeach the President. It is likely that the Democratic Congress would seek to draw in the reins of American foreign policy, and potentially the rapid accumulation of debt by the President though it is hard to find Democrat fiscal hawks. In this regard, a potential market reaction may be a rally in Treasuries should the Democrats enjoy a successful mid-term campaign.
They are also likely to want to slow the build-out of data centres, and AI infrastructure in general, which as an economic activity is dwarfing activity in other sectors – be they manufacturing or construction, and has become a major focal point in state-level elections. Naturally, the emergence of such a policy across Congress would dent the speed of AI infrastructure build-out, which itself may not be a bad thing. But, the financial upshot is that a Democrat win in the Senate (and House) may be the catalyst to trigger a significant shift from US equities to bonds, and the President may well blame them for any resulting market volatility.
When the dust settles on the midterms, the 2028 presidential race will start.
Have a great week ahead, Mike
Trade wars can have long-running, unintended consequences. The Smoot-Hawley Act of 1930, widely regarded as a catalyst to the Great Depression, contained a clause (section 305) that permitted the banning of obscene materials, a classification that (in the US) covered James Joyce’s Ulysses. Joyce’s publisher, keen to sell the book in the US, brought a test case under the Smoot Hawley Act (United States vs. One Book Called ‘Ulysses’), and the resulting verdict that the book was not ‘obscene’ made Joyce’s text a bestseller in the US and changed American obscenity laws.
A more serious case was the consequence of the Opium Wars, which ended with Hong Kong ceded to Britain, and began what China recalls as its ‘century of humiliation’, a perspective that still colours Beijing’s view of the West. In 1997, Chris Patten presided over the handover of Hong Kong to China, and in 2020 the introduction of the national security law drew Hong Kong legally, institutionally and politically back to China, with little protest from the West, and in my view, this is the defining event that marks the end of globalization as we knew it.
A key institution in the process of globalization was the World Trade Organisation (WTO), which in its early incarnation as GATT (General Agreement on Trade and Tariffs) enjoyed strong leadership under Peter Sutherand and later Pascal Lamy, but is now defunct.
Beyond its trade agreement rounds, the most consequential event for the WTO was the decision to admit China in 2001. The move was approved by President Bill Clinton at a time when there was an uneven power balance between the US and China and, at the time, Clinton described China’s economic relationship with the USA as ‘the equivalent of a one-way street’ (arguing that it was a highly attractive opportunity).
The trade, manufacturing and financial relationship between China and the West formed the basis of globalization, and it is the evolution of China from a provider of cheap labour into an economic powerhouse, together with the failure of the West to hold it to the terms of WTO, that has led to the breakdown of globalization. Indeed, many expected that the second Trump presidency would pick up where the first one left off, with a hostile trade stance on China (in 2018 Marco Rubio released a very hawkish report on China ‘The World that China Made’).
Now, Europe rather than the US, may be the one to pick a trade fight with China.
China’s growing prowess in technology, intense domestic industrial competition, coupled with large quantities of state aid for ‘champion’ firms, and the need to replace a deflating real estate sector with a manufacturing boom, have created a surplus in/of manufactured goods, which China has opportunistically dumped on the European market (known as the China shock 2.0), to the consternation of auto manufacturers, chemical producers and pharmaceutical firms in the EU.
Until very recently, the EU has permitted this to continue, for at least two reasons. The first is that EU trade policy is very product-focused in terms of its corrective measures, and the second is that there has been no strong consensus amongst the large European countries on how to deal with China. For example, in his 946 page memoir “La diplomatie n’est pas un dîner de gala’ (a play on Mao’s line that a revolution is not a dinner party) the former French ambassador to China, Claude Martin states that the lack of a coherent, watertight view on China by the EU (with policy measures to support), meant that China could divide and conquer across European capitals.
That is apparently changing. In recent weeks, commentators and industry bodies in the major countries, notably France and Germany, have been striking a bold and hawkish note on China, and this much was reflected in a major development with the issue of a letter by French and German presidents to the EC president, where they call for a much tougher stance on China.
In my view, there are three mistaken elements in the French/German stance, a lamentable view of Europe as the victim, a lack of urgency to get European industry to reform and become more competitive (notably few of the Draghi recommendations are in place), and third, the lack of an even more aggressive view on China in the sense that its economy may be even weaker than many think.
Diplomatically, the move is being presented as a ‘conversion’ by the two governments, each led by intensely unpopular figures (Macron’s ratings are at an all-time low and Merz’ is not far behind).
There are two elements to note in the letter, which aims to protect key European industries such as chemicals, pharmaceuticals and autos in particular. The first is a diversification instrument that will safeguard supply chains from over-reliance on Chinese goods and inputs, and the second powerful measure aims to exclude Chinese companies (China is not mentioned in the document but the sense is that it is very much the target) from the EU market where trade dumping produces severe and systematic distortions. The implementation of such a measure could be rapid and would need a majority of EU states to block it.
EU trade commissioner, Maros Sefcovic spent last week in China, trying to extract a commitment from Beijing to limit the flow of Chinese goods to Europe. My sense is that the polite apathy that greeted him (as I write there is talk of an agreement on are earths) means that China has little intention of striking a reliable deal, and that a trade confrontation between Europe and China in early 2027 is something European businesses need to prepare for.
Have a great week ahead, Mike
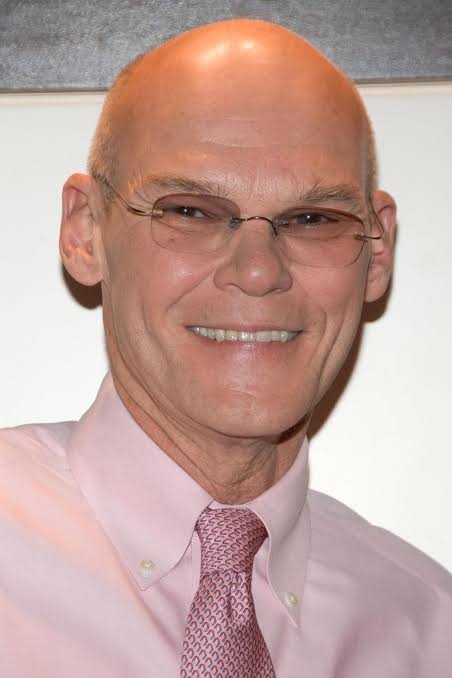
In the coming weeks we will likely hear James Carville’s name more often. Carville earned his fame as political adviser to the Democrats (his wife Mary Matalin was an equally famous Republican adviser), and is known for his pithy advice, having told the Clinton Democrats that ‘It’s the economy, stupid!’, and recently counselled them to ‘play dead’, whilst the Trump Republicans continue to make mistakes.
It might be expected that Carville will become sought after for his views on the forthcoming mid-terms, but it is more likely we will hear him quoted in relation to the bond market. In the context of mostly dull economists, journalists in need of a good bond market quote turn to Carville who stated that ‘’I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.”
He said it in 1994, when US bond yields had pushed out to 8%, forcing Treasury Secretary Robert Rubin into a four-year deficit reduction programme – built on a rare moment of constructive bipartisanship – that halved bond yields and eventually produced a budget surplus. That kind of policy foresight, bipartisanship and political leadership is rare today; what endures is the bond market’s reputation as a powerful, intimidating beast.
Today, the bond market is back, and it is intimidating investors, governments and soon, the public. For all too long, bond buying by central banks had a soporific effect on bond prices, dulling them to the rising fiscal risks that have now enveloped most of the major economies. A couple of years ago we compared the effect of central bank liquidity to the storyline in the Danish film ‘Druk’ (which I recommend) where a group of teachers experiment with a permanent state of tipsiness. Central banks are now withdrawing liquidity, bond markets are sober and alive to the world and are pointing out various truths.
The first of these is that the ‘debt purgatory’ has commenced, precisely when the US Treasury Secretary made a series of failed interventions in currency and bond markets, demonstrating – in the spirit of Carville’s quote – that the bond market is more powerful than the government. In that respect, a threshold has been crossed where finance ministers may no longer be able to run near record deficits (in the context of economic expansion) and gargantuan debt levels. Scott Bessent, who has displayed a fetish for controlling market prices, may soon need either to start trimming spending, or to raise taxes (unlikely).
In France, the debate on the budget starts in earnest next week, in the context of the highest spread between French and German bond yields since 2012, and the woeful performance of the CAC 40 (in the past three years the Spanish and Italian stock markets have outperformed it by close to 90% and 75% respectively). To that end, debt, deficits and bond markets will dominate politics. For example, a recent Institute of International Finance (IIF) shows that the US spends more on interest payments (4% of GDP) than at any point in the last thirty years. In that context, it is likely that bond markets may only be calmed when governments make a serious effort to mend their finances, and when central banks enact further rate increases. This will prove to be a tough run into and beyond Christmas.
The second germane element of the rise in bond yields (which are only returning to their 150 year averages), is reflexivity, a word coined by George Soros to describe the ways in which moves in asset prices can cause effects in the real economy (and in other asset prices).
Higher bond yields should curb risk appetite and slow the economy. In previous economic cycles the thinking was that higher bond yields led to higher mortgage rates and thus a sluggish property market. The difference today is that many of the ‘Baby-Boomer’ generation have paid off their mortgages, or locked in mortgage rates at low levels, and the US middle-class has never been wealthier, and less rate sensitive (for example a new book ‘The Everywhere Millionaire’ by Owen Zidar and Eric Zwick traces the origins of the wealth of the 3 million Americans with over USD 25 million in wealth each and this effect is evident through the rest of the US wealth pyramid).
In other areas, the reflexive effect of bond yields may just be beginning and is already manifesting itself in the very riskier reaches of the corporate bond market (high yield/CCC rated bond yields are rising) and may soon take its toll on cyclical commodity prices (copper and oil).
The puzzle, optically at least, is that US equities have not registered the rise on bond yields. However, within the equity market, the many stocks have been weak over the past month (for example household ‘names’ Goldman Sachs and Boeing have fallen close to 20% since mid July) but headline indices have been kept higher by the small number of mega-cap AI related stocks (Intel, NVIDIA). Unlike US households who have in general been deleveraging, the AI complex is busy piling on debt. A sign of this is that UBS recently initiated a new publication, the ‘AI Debt Financing Monitor’. Experience tells me that the initiation of publications that herald the arrival of new asset classes is always a warning sign. To that end, the time to buy bonds is when yields rise to levels that brings hyperscaler debt raises to a halt.
Have a great week ahead, Mike
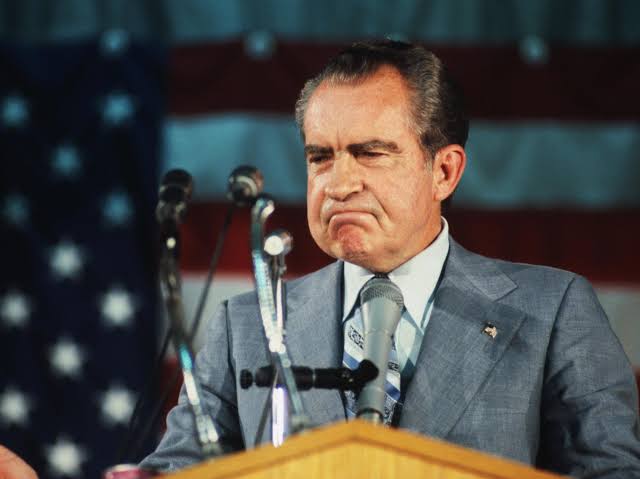
For much of the past fifty years, Richard Nixon, or Tricky Dicky as he became known, was held up as an example of one of the most dishonourable American presidents. In August 1974, Nixon, towards the end of his presidential term, resigned over the Watergate scandal, rather than face a near certain impeachment. The Watergate ‘Caper’ about which there is a very good, new film by Shane O’Sullivan (the cousin), involved a team of clandestine operatives linked to Nixon, breaking into Democratic party headquarters and planting evesdropping equipment. The revelation of the Watergate scandal made journalists Carl Bernstein and Bob Woodward of the Washington Post world famous.
Nixon wasn’t all bad. In the early years of his presidency, he enjoyed very high approval ratings. He, with the help of Henry Kissinger, opened up China diplomatically, pursued better relations with Russia, and ended the draft. Rankings of American presidents (from the likes of the Wall Street Journal, the Siena College Research Institute and C-SPAN) place Nixon on average in about 32nd place out of 47 presidents.
However, there is a strong view that his Vice President, Spiro Agnew, was one of the worst to hold that office. Agnew was known for his venality and had received envelopes of cash whilst in the White House. He is the only Vice President to have left office because of a criminal probe.
Apart from the release of ‘The Watergate Caper’ the reason we need to recall Nixon’s behaviour, is that it is a (low) benchmark that helps us understand how far standards in public life have fallen. Indeed, some weeks ago Vice President Vance stated that ‘If Watergate happened tomorrow, it would be a 12-hour news story”. Reflecting this, the USA is at its lowest point in the Transparency International Corruption Perception rankings, in 29th place (Denmark is the least corrupt country), and corruption is a topic increasingly taken up by commentators, Andrew Cockburn’s book ‘Washington is Burning’ and Anne Applebaum’s Atlantic magazine article ‘Empire of Grift’ are just two recent examples.
Last week, press freedom in the US took a hit and there are warning signs of a similar erosion in the rule of law within the US itself: the Department of Justice has terminated a record number of pending cases and grown notably lax on fraud, procurement manipulation and even criminal prosecutions, and UCLA’s Safeguarding Justice Project surveying elite lawyers, federal judges, political scientists and law professors, finds that the rule of law in America is at its weakest point in at least a decade.
What is dispiriting, is that few people appear to care that American politics is becoming more venal. For example, stock market investors track the share purchases of congressmen and women, who outperform the market with alarming ease. The coming mid-terms will also represent a test.
The other, related question we need to ask, is does it matter for the economy. In general, to parse reams of research from the World Bank, who produce an excellent database of indicators on the rule of law, governance and corruption, and whose regular ‘Governance Matters’ research papers are a worthwhile source.
There is a strong, positive correlation between factors like the rule of law and long-term economic growth. In particular, small, open economies (i.e. Singapore) are an example, and as a disparate group they have made a common cause and economic ‘recipe’ of their attachment to good governance, institutions and the rule of law. Also, award winning research, such as the book ‘Why nations Fail?’ by Simon Johnson and Daron Acemoglu, has helped to reinforce this view. In general, economists have found that corruption lowers growth by reducing investment, the higher costs and uncertainty arising from corruption cause investors to become more circumspect.
The most interesting cases though, are when countries change from being corrupt to ‘normal’, or vice versa. In the aftermath of the post communist era, Georgia made a concerted and now well documented effort to eliminate corruption, with initially impressive economic results. It now ranks 56th out of 182 countries in the Transparency International list, on a par with Greece, but a distance ahead of Russia (157th place).
Then, on the way down, perhaps the best example is Venezuela, a relatively stable, prosperous country up until the advent of Hugo Chavez. Hungary under Viktor Orban, and South Africa, are other convincing cases. None of these examples bode well for the US, where the damage to the rule of law is disguised by the hubris of the AI capital spending boom.
As a parting thought, I recommend readers watch Robert Redford and Dustin Hoffman in ‘All the President’s Men’, the best quote of which is ‘follow the money’.
Have a great week ahead, Mike
Ursula von der Leyen, the European Commission president, once led a mysterious life. Owing to death threats by the Red Army Faction against her father Ernst Albrecht, a prominent Christian Democrat, and suspicions that she might be kidnapped, she was sent to study in London, under the alias ‘Rose Ladson’. As such, von der Leyen is unfortunately acquainted with the types of security threats that are live across Europe.
In her State of the Union speech last Wednesday, geopolitics and security had top billing. In particular, Russia’s hybrid war in Europe (from sabotage to manipulation of elections, as we highlighted in a recent note, Russia Risks Rising) is enunciated as the main risk, and institutionalized measures are being put in place to counteract this. A full European Security Strategy will be unveiled this autumn, part of which is a NATO style Article 4 measure, where one European nation (likely including Norway, the UK and Canada) can draw upon the support of others. Indeed, the sense is of a Europe broadly preparing to assume the structures and processes of NATO, in the event that the US disengages from it.
It is likely that a component part of the new European Security Strategy will be a European Security Council, whose role may be to run crisis management, cross country procurement and to liaise with close EU partners such as the UK and Canada. In keeping with Jean Monnet’s dictum that Europe only moves forward in a crisis, it has required a war in Ukraine, conflagration across the Middle East, not to mention a very unexpected shift in foreign policy by the White House, to get Europe to this point. Given that its EU level diplomatic service has effectively failed, partly because of national level competences and rivalries, the EC needs to take care that the same does not happen in the realm of security.
One concern, that is so far registering behind the scenes, is a growing rivalry and even antagonism between the French and Germans in the areas of innovation, battle readiness and funding. Another more profound concern is that different EU countries have very disparate levels of competence when it comes to intelligence gathering and operations.
European nation states have been spying professionally for centuries, and Christopher Andrew’s excellent book ‘The Secret World’ makes this very clear. Some have allowed these skills to wither, and others have had to pivot to meet new challenges. Spain’s intelligence effort was almost entirely focused on domestic threats (separatists) up until the lethal Madrid bombings in March 2004, and thereafter it had to quickly build up an external facing capability. Other nations, from Sweden to Japan, are now augmenting their external-facing intelligence services.
In this context, the French magazine L’Express has, based on interviews with sixty former spies (including some agency chiefs), scored and ranked Europe’s intelligence agencies, and there is a very good discussion of the process in the Collimateur podcast. The runaway winner is MI6, on 261 points, followed by France’s DGSE on 169 points (judges apparently gave them high marks for their field operations), followed by the Netherlands on 97 points (renowned for their discretion and cyber capabilities). Then, maybe unsurprisingly in fourth is Ukraine’s secret service, given the extent of the challenges it has faced. Germany comes some way behind in fifth, followed mostly by the Nordic countries, Poland and Estonia.
A number of large countries are well down the list, such as Spain and notably Italy (Estonia gets 27 points as compared to Italy’s 9 points), as are wealthier countries Switzerland and Belgium. Austria and Portugal prop up the end of the list, and the likes of Hungary and Slovakia get zero scores, and according to the authors of the research report, are largely untrusted. Ireland did not feature. There are broadly two axes of strength, London/Paris and Den Haag, and the other to the north (Nordics/Baltics down to Poland). The south of Europe is weak, as are a number of EU members to the east.
Today, the majority of the intelligence agencies in Europe are united by the challenge presented by Russia, not to mention hybrid actors (gangs and cyber-attack groups) as well as some powerful corporate intelligence teams. There remains insufficient trust between many of them, and the opportunity for hostile actors to target weaker states is significant. Lurking behind the ranking is an ongoing reliance on US intelligence.
By that mark, Europe’s spies have a long way to go.
Have a great week ahead, Mike

